
How much retirement savings do Americans actually have?
The Federal Reserve released the results of its 2025 Survey of Consumer Finances on October 9, 2026. Among families that have a retirement account, the median balance is about $106,000 and the average is about $451,100. The gap between those two numbers matters. A relatively small number of very large accounts pulls the average far above what a typical family holds.
Many families are not in that group at all. Roughly 45% of all families, and about 51% of families under 35, had no retirement account in 2025. These figures describe account holders and families, not only people approaching retirement, and the Fed’s tables break balances out by age. Even so, they point to the same reality: for a large share of households, retirement savings are either missing or too small to serve as the main source of retirement income.
What a retirement savings balance pays you each year
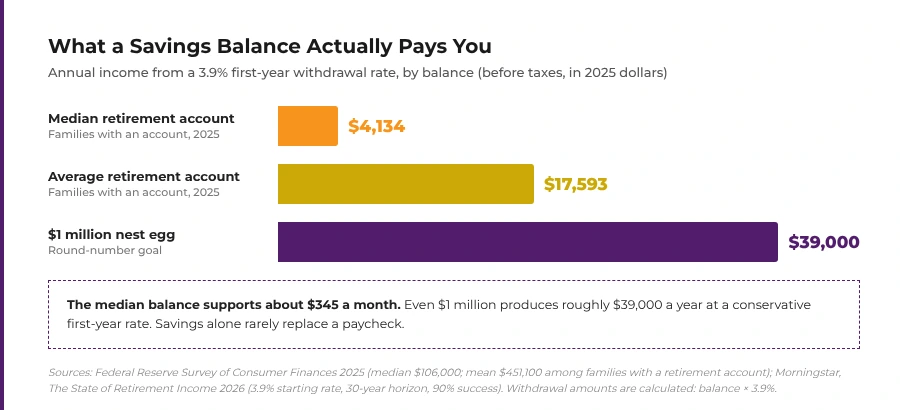
A balance only matters for the income it can safely produce. Morningstar’s 2026 State of Retirement Income report puts the highest safe starting withdrawal rate at 3.9% for a 30-year retirement, with a 90% chance the money lasts, assuming a portfolio that is 30% to 50% stocks. That rate is for a retiree who wants steady, inflation-adjusted spending. Retirees willing to adjust their spending in weak markets may be able to withdraw more.
Apply that rate to the balances above and the scale becomes clear. The median account of $106,000 produces about $4,100 in the first year, or roughly $345 a month. The average account produces about $17,600. Even a $1 million nest egg produces about $39,000 a year. These are calculated, pre-tax figures, and Social Security and other income sit on top of them. The point is proportion: a savings balance on its own rarely replaces a paycheck.
Error: Campaign not found.
Social Security helps, but it was designed to replace only part of pre-retirement earnings, not all of them. Most retirees need their savings to fill the remaining gap, which is why the size of the gap, and not just the size of the balance, is the number worth watching.
Where a retiree lives changes the math further. A December 2025 GoBankingRates analysis found that $1 million would fund just nine years of spending for the average retiree in Hawaii, and under 15 years in 16 other states, including every West Coast state. That study divides $1 million by national average spending for people 65 and older, scaled by a state cost-of-living index, so it ignores Social Security and investment returns. It illustrates how quickly a fixed balance can be spent. It is not a forecast.
Why rising costs outrun a fixed savings balance
A savings balance is a fixed number. The things it has to pay for are not. Three pressures work against it at the same time: inflation, health care costs and longer lives.
Inflation shrinks what a fixed balance buys
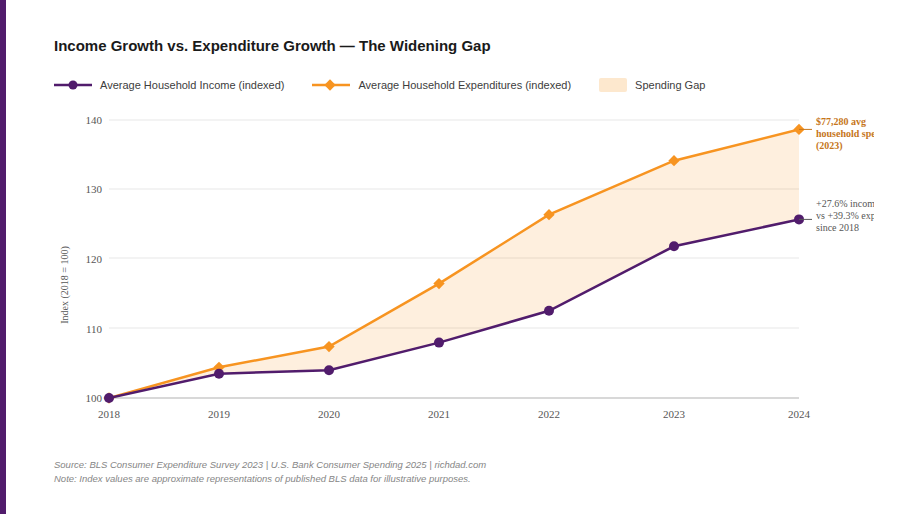
Even modest inflation compounds. At an illustrative 3% a year, $60,000 of annual spending today becomes about $108,400 in 20 years and about $145,600 in 30 years. A retirement that starts at 65 can easily run that long, so income that looks comfortable in year one can fall well short by year 25. Household budgets are already moving this way: the index below shows average household expenditures climbing faster than average household income since 2018.
Inflation hurts most when income is fixed. Income that tends to rise with prices, such as rent from property or profit from a business, adjusts over time. A fixed withdrawal does not. For a deeper look at building income that lasts, see How to Make Your Retirement Savings Last.
Health care is the cost that grows fastest
Fidelity estimates that a single 65-year-old retiring in 2025 will spend about $172,500 on health care and medical expenses over retirement, net of taxes. In 2023 the estimate was $157,500, and in 2002 it was $80,000, so it has more than doubled. The 2025 figure leaves out long-term care, over-the-counter drugs and most dental services, and it assumes no employer retiree coverage.
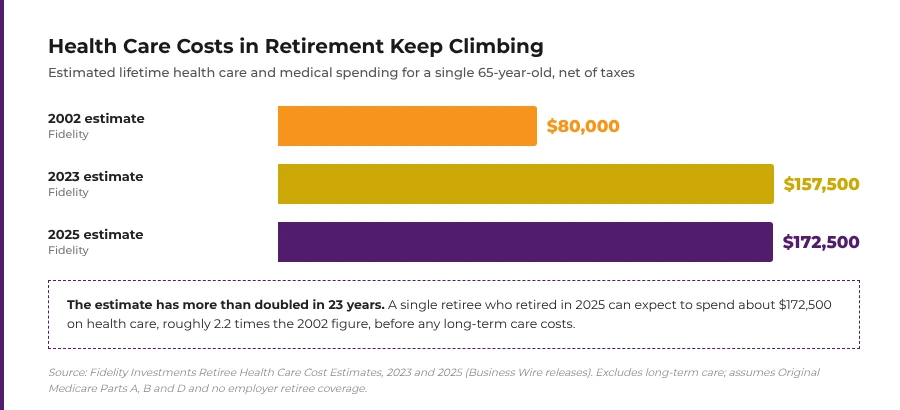
Total retirement spending can ease in later years as people travel and shop less. Health care is the exception, because its costs tend to rise with age. That makes it a poor fit for a plan that assumes a flat withdrawal from a balance that is shrinking.
Error: Campaign not found.
Longer lives stretch the timeline
Fidelity has noted that retirement can often last 25 years or more, and Morningstar plans around 30. Each added year brings another year of inflation and another year of withdrawals. That is why a number that looks large at 65 can look small at 85.
Early market losses do lasting damage
Timing adds another risk. A weak market in the first years of retirement is especially damaging, because withdrawals made while prices are down lock in the loss and leave less to recover when markets turn. This is often called sequence-of-returns risk, and it is one reason safe withdrawal rates are set conservatively. Two retirees with the same average return over 30 years can end up in very different places depending on when the bad years arrive.
Why a bigger savings number is not a plan
The natural response is to save more, and saving more helps. It runs into two limits. The first is the starting point. Many households have very little to build on: the chart below shows the median American adult holds about $500 in emergency savings, according to Empower’s 2024 study, and the Federal Reserve found that about 30% of Americans could not cover three months of expenses by any means.
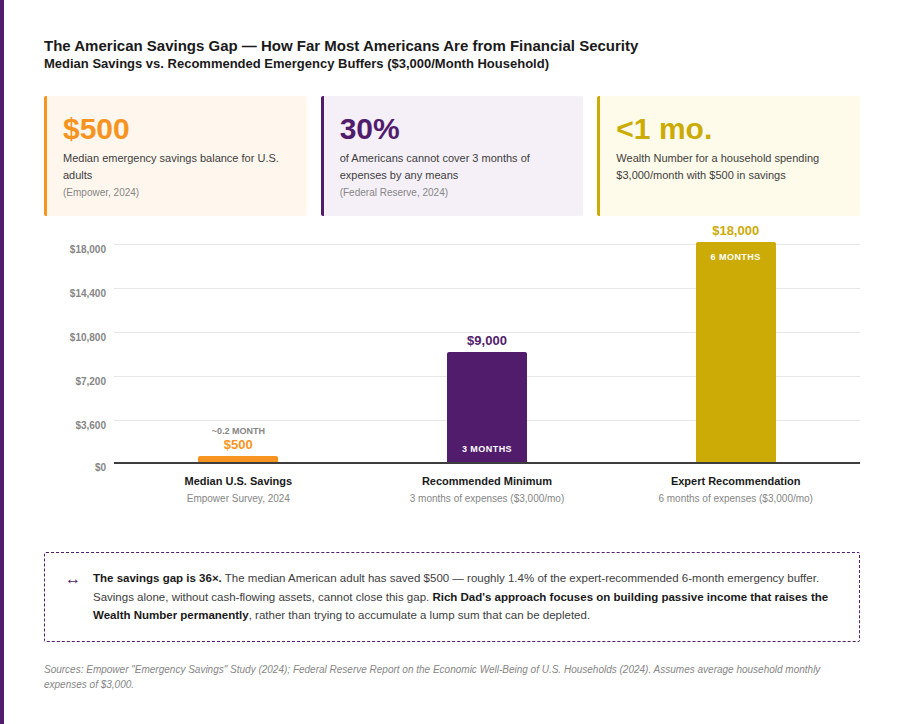
The second limit is that the target moves. Costs rise, returns change, and the safe withdrawal rate itself shifts from year to year. Morningstar’s figure was 3.7% for 2025 and 3.9% for 2026. A plan that depends on one number staying right for 30 years leaves little room for error.
What Rich Dad suggests building alongside savings
Rich Dad’s long-standing view is that savings are money, while assets are what produce money. In practice the difference is simple. A retiree living on savings spends down principal. A retiree living on income-producing assets spends the income and leaves the principal intact. Cash-flowing assets such as rental property, a small business or dividend-paying investments can also rise with prices instead of being eroded by them. Rich Dad’s approach to real estate investing is built around this idea.
This is not only a strategy for the young. Kauffman Foundation data show that in 2021, 22.8% of new entrepreneurs were between 55 and 64, up from 14.8% in 1996. More people in their fifties and sixties are choosing to build income rather than rely only on a balance. None of this is guaranteed, and businesses and investments carry real risk, so it makes sense to test ideas on a small scale and to get professional advice.
A practical first step is to measure the gap. Estimate yearly spending in retirement, subtract guaranteed income such as Social Security, then see how much of the remainder your savings could produce at about 3.9%. Whatever is left over is the income you would need to build somewhere else.
Savings are a starting point, not a finish line
Retirement savings can’t keep up on their own because the problem is structural. Balances are modest for most families, a safe withdrawal rate turns even a large balance into a modest income, and costs rise for decades. Saving still matters, because it funds everything else. The shift Rich Dad encourages is to treat savings as the seed money for assets that produce income, so that a retirement does not depend on a balance that shrinks every year.
Error: Campaign not found.
FAQs
It depends on what you spend and what other income you have. A simple starting point is to take yearly spending, subtract guaranteed income such as Social Security, and divide the remainder by 3.9%, Morningstar’s 2026 safe starting withdrawal rate for a 30-year retirement. For example, $40,000 a year of spending not covered by other income points to about $1.03 million. Flexible spending, longer or shorter retirements and your investment mix all change the answer.
A savings balance is fixed, while inflation, health care costs and longer lifespans keep raising what it has to cover. Withdrawing from a balance also shrinks the principal that produces future growth. Income that rises with prices, such as rent or business profit, is not affected in the same way.
It can be for some people and not for others. At a 3.9% first-year withdrawal rate, $1 million produces about $39,000 a year before taxes. Where you live, your health costs, Social Security and how long you need the money to last all matter. In high-cost states, a $1 million balance can be spent much faster.
Morningstar estimates 3.9% as the highest safe starting rate for a 30-year retirement with a 90% chance of success, up from 3.7% for 2025. The rate is not a rule. It changes with market conditions, your portfolio mix and the length of your retirement, and retirees willing to flex their spending may be able to start higher.
Total spending often eases in later years, but health care is the exception. Fidelity estimates a single 65-year-old retiring in 2025 will spend about $172,500 on health care, excluding long-term care. Many retirees also find their actual spending differs from their plan, so building in a margin is sensible.
Many people pair savings with income-producing assets, such as rental real estate, a business or dividend-paying investments, so that income does not depend entirely on drawing down a balance. These carry risk and are not right for everyone, so consider speaking with a licensed financial professional.